All Categories
Featured
Table of Contents
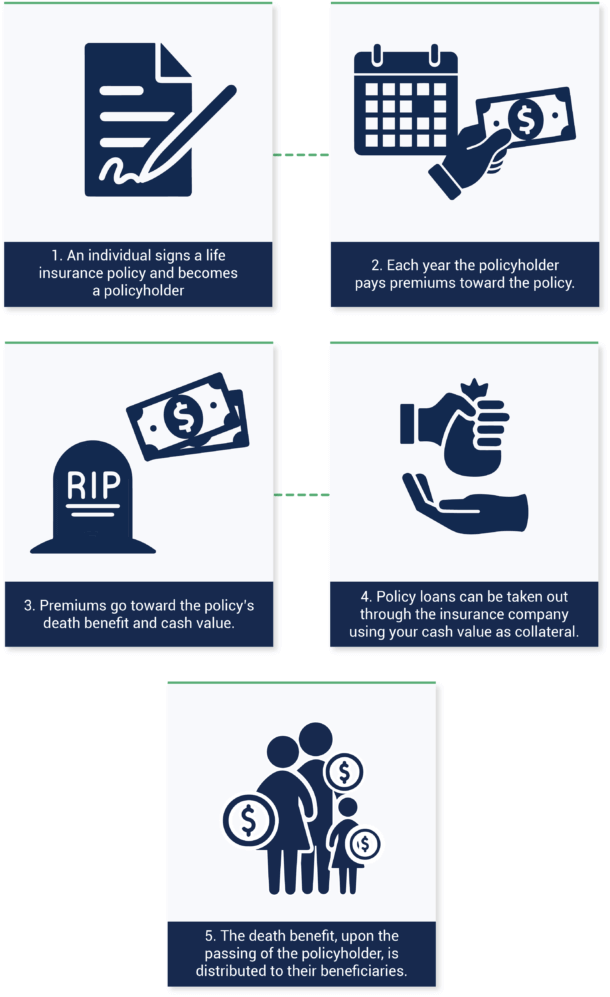
As soon as the very first premium is paid, the entire death advantage is set aside for your family. Earnings tax-free survivor benefit: The death benefit of a life insurance coverage policy is not usually subject to federal earnings taxes. Tax-deferred development: The growth of money worth within entire life insurance is tax-deferred while the funds remain in the policy.
This suggests withdrawals to the level of expense basis are thought about an income tax-free return of cost basis. Tax-favorable access to money worth loans for any reason: Throughout the insured's life, cash worth loans taken versus an entire life policy are ruled out to be a taxable occasion, despite the fact that the policy may have a big gain in excess of premiums paid.
Self-funding: The policy can pay for itself with time by using dividends to pay premiums, which adds to the policy's cost savings part. Impairment protection: An entire life policy can continue to be moneyed even if you are disabled. When you elect the Waiver of Premium rider9, if you suffer a certifying disability, your policy will continue to offer survivor benefit protection, have cash worth development, and pay dividends even while you aren't paying premiums.

10Distribution: If properly carried out, life insurance assists avoid probate and can provide beneficiaries with higher privacy than may be managed by a will; a will becomes public once probated, whereas survivor benefit circulations are typically personal, contractually driven deals. Once a policy loan has been taken, the yearly dividend can be utilized to assist repay the policy loan.
Functions, provisions, and expenses vary from one insurer to the next, and each entire life agreement is unique to the insurance policy holder. Entire life insurance coverage rates depend upon elements such as age, health, and protection quantity, so it is essential to consider these when examining policies. Normally speaking, there are two basic types of payment structures for whole life: Level premium entire life: This is the most typical kind of whole life insurance coverage.
Senior Hearing Aid CoverageLife Insurance Benefits for Veterans
Limited payment whole life: This type of policy has a fixed level premium like a level premium whole life policy, but the premium is just payable for a fixed amount of time. The advantage is that they are guaranteed to be paid up at the end of the payment duration, so no payment is required at later ages.
Their accessibility and cost depends upon the policy and the insurance provider. In addition to the Waiver of Premium rider pointed out above, some other alternatives offered by Guardian consist of: Paid-Up Additions Rider: The PUA rider can help increase the build-up of tax-deferred cash worths and death advantage. The greater the premium paid into the rider, the greater the protection afforded by the policy.

It offers you an unique chance for index-linked upside capacity and the flooring guarantees that your year-to-year drawback market exposure is limited. Accidental Survivor Benefit: Provides an additional death benefit if death takes place by unintentional bodily injury. Accelerated Benefit Rider: Provides accelerated advantages, enabling you to access a portion of the survivor benefit early if you are diagnosed with a chronic or terminal illness.
Understanding Whole Life Insurance Functions
Surefire Insurability Option (GIO): Provides the policy owner the right to buy extra insurance without proof of insurability. The GIO can end up being a lot more valuable in the occasion of disability: A guaranteed who is handicapped and has their premium waived might exercise the GIO rider, and Guardian will pay the premium on the new policy An entire life insurance policy is one of the most essential financial purchases you can make.
12 Comparing life insurance business and their life insurance offerings such as entire life, universal life, fixed premiums, ensured survivor benefit, and money value growth is necessary to discovering the ideal policy for your needs. There are trustworthy, independent sources for financial strength rankings, such as A.M. Best, Moody's, Requirement & Poor's and Fitch.
Discuss your circumstance with an insurance expert or monetary expert who comprehends entire life insurance coverage and can guide you to the solution that finest meets your requirements. If you don't know such a professional, ask a friend or colleague for a recommendation. Or, Guardian can link you to a monetary expert who can assist.
A whole life policy has cash value that grows gradually. You can cash it out to assist supplement retirement, or obtain against it at any time, for any factor. Entire life policies have a component referred to as the policy's money value: A portion of your premium dollars can grow gradually on a tax-deferred basis, so you do not pay taxes on the gains.

Latest Posts

Why San Bernardino Families Choose Term Life Insurance for Safety
The Financial Impact of Medigap Birthday Rules for Seniors

Comparing PPO Vs HMO Plans